Published: Friday, 2 October 2026 | Reading Time: 10 minutes | By: Megawatt Financial Services | License: NCRDC3803
| TARGET KEYWORD: DEBT REVIEW REMOVAL CASE STUDY • META DESCRIPTION (156 chars): A complete debt review removal case study: R184,500 settled, a hidden R8,400 residual, and Form 19 clearance in 60 days. Every step documented. Read it now. |
Most debt review removal advice is generic. This is not. In this case study, we open a real 2026 file — every document, every negotiation, every day — so you can see exactly what a lawful, professional removal looks like from mandate to clearance certificate.
Our client, whom we’ll call Sipho, is a 38-year-old logistics supervisor from Polokwane. He entered debt review in 2020 owing R184,500 across six creditors, settled the restructured amounts during 2025, and spent early 2026 wondering why his credit record still said ‘flagged’. By October, he was clear.
If your situation echoes Sipho’s — debt paid or nearly paid, flag still up — this case study is your roadmap. And the first step on it is free: WhatsApp +27 81 338 7728.
Day 0: The Audit That Found What Everyone Else Missed
Sipho’s WhatsApp message to us was one line: ‘Everything is paid, why am I still flagged?’ Within 24 hours we had pulled his reports from TransUnion, Experian, XDS and Compuscan, plus his NCR Debt Help System record. The audit found three problems: three settled accounts still reporting as open, one residual balance of R8,400 that had never been renegotiated or formally allocated, and a missing paid-up letter from his largest creditor.
This pattern — ‘the debt is gone, the paperwork isn’t’ — is the single most common cause of stalled clearances in South Africa. No court application, no dispute, no shortcut fixes it. Evidence does.
Days 7–38: Negotiation and Settlement
With a signed mandate, our counsellors approached each creditor. The three ‘open’ accounts were formally closed in writing within two weeks. The R8,400 residual — a leftover from an early settlement that had never been documented — was negotiated down to R5,900, a 30% saving, and settled from Sipho’s confirmed budget in a single payment.
By day 38, every restructured account carried either a zero balance or a signed settlement letter. That is the legal threshold for clearance under section 71 of the National Credit Act — and the point at which most DIY attempts stall for months, because they lack exactly this paper trail.
Days 38–60: The Clearance Certificate
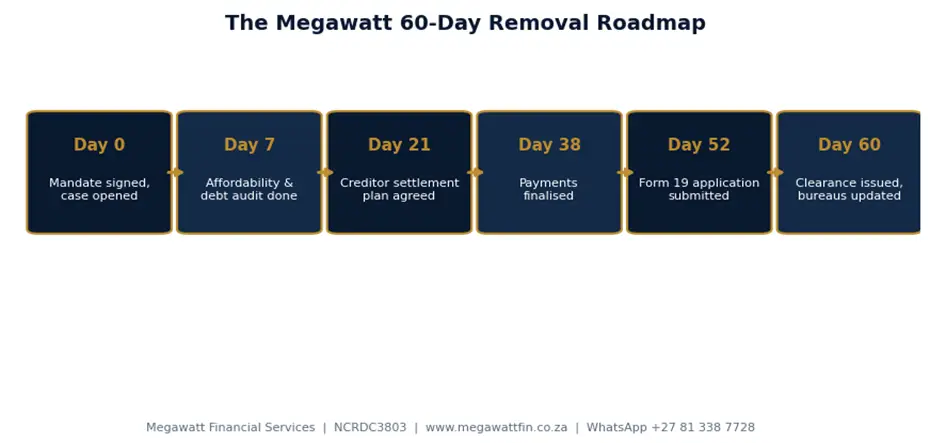
We assembled the compliance file — ID, statements, paid-up and settlement letters — and prepared the Form 19 clearance certificate. It was issued on day 52, lodged with all four bureaus and the NCR registry, and by day 60 Sipho’s record showed clear everywhere. His score moved from 511 to 634 within the following 30 days — without a single new account.
Total elapsed time from mandate to verified clearance: 60 days. Total surprises along the way: none — because the audit had already found them.
What This Case Study Teaches You
First: settlement and clearance are separate legal events, and the certificate never issues itself. Second: residuals matter — R8,400 nearly cost Sipho another year. Third: speed is a function of preparation. A complete document pack is what separates a 60-day file from a six-month one.
Every Megawatt file runs this same sequence: audit, negotiate, settle, certify, verify. It is not glamorous. It is simply what works.
Sipho’s File: Day-by-Day Milestones
| Stage | Day | What happened |
| Mandate signed & audit | 0 | All bureau reports + NCR registry pulled |
| Problems identified | 2 | 3 open accounts, R8,400 residual, 1 missing letter |
| Creditor engagement | 7–21 | Accounts closed in writing |
| Residual negotiated & settled | 21–38 | R8,400 → R5,900, settled in full |
| Form 19 issued | 52 | Signed by registered debt counsellor |
| All bureaus verified clear | 60 | Written confirmation to client |
Infographic — Article 02 | Alt text: “debt review removal case study infographic — Megawatt”
What This Means for You
- Finance approved for a replacement vehicle six weeks after clearance
- Credit score up 123 points in 30 days with no new credit
- Removed from the NCR Debt Help System registry
- Zero further debt review distribution fees
- Documented proof of clearance for future credit applications
Common Mistakes to Avoid
I. Assuming ‘paid up’ means ‘clear’: Until the Form 19 is issued and lodged, the flag stays — legally and practically.
II. Settling residuals without a settlement letter: Verbal or emailed ‘it’s sorted’ means nothing. Only signed letters satisfy the compliance file.
III. Disputing accurate listings: Bureaus reinstate verified data. Disputes are for errors, not for shortcuts — and misuse can flag you for fraud.
IV. Skipping the audit to save time: Sipho’s three hidden problems would have surfaced mid-application and cost months. The audit IS the time-saver.
V. Using an unregistered ‘agent’: Only a registered debt counsellor can issue Form 19. An agent’s ‘clearance’ is a piece of paper with no legal force.
What Sipho’s Clearance Cost (vs DIY Market Rates)
| Item | Typical DIY/market cost | Sipho’s outcome |
| Assessment & audit | R300–R500 | FREE |
| Residual negotiation | R1,500–R3,500 | Part of fixed fee — saved R2,500 on the balance itself |
| Form 19 issuance & lodgement | R500–R1,500 | Included in fixed fee |
| 4-bureau verification | R400–R800 | Included |
| Hidden costs | Unknown | None — quote matched invoice to the rand |
Frequently Asked Questions
Q: Is 60 days guaranteed?
No ethical firm guarantees timelines, because creditors and bureaus are third parties. What we guarantee is the process: complete files in our 2026 cohort cleared between 39 and 67 days.
Q: What made Sipho’s file ‘fast’?
Nothing exotic — a complete audit on day 0 meant zero surprises later. Preparation is 80% of speed.
Q: What if my file is more complicated?
Multiple creditors, court orders or foreign income extend timelines. Your free assessment maps your actual route and range.
Q: Do you share my details in case studies?
Never without written consent. Names are always changed; figures are only ever published as they appear in the clearance file.
Q: Can I start with just the audit?
Yes. The assessment and audit are free and no-obligation. Many clients use them simply to learn their status — that is fine with us.
Why Choose Megawatt Financial Services?
| Feature | Megawatt | Other Providers |
| NCR Registration | NCRDC3803 | Varies |
| Free Assessment | Yes | Often R300–R500 |
| Fixed Pricing | No hidden fees | Often variable |
| All 4 Bureaus | Submitted to all | Often only 1–2 |
| Local Branches | Mokopane & Makhado | Often online-only |
| WhatsApp Support | +27 81 338 7728 | Often phone-only |
| Legal Representation | Included | Often extra cost |
Ready to Regain Control? Here’s Your Next Step
You’ve read the facts. Now take the two-minute step that changes everything. WhatsApp Megawatt Financial Services on +27 81 338 7728 — private, confidential, no paperwork required to start. Phone: 0861 MEGA-DC (0861 6342 32) | Email: info@megawattfin.co.za | Website: www.megawattfin.co.za
Our Branches
Branch 01 — Mokopane: 53 Retief Street, Office 1B Jaco Mari Building, Mokopane, 0600 | Branch 02 — Makhado: Office No: 5 Maranatha Centre, 93 Burger Street, Makhado, 0920 (Next to Old AVBOB)
| Trusted Debt Specialists Since 2019 | License: NCRDC3803 | Regain Control. Rebuild Your Future. |