Published: Monday, 19 October 2026 | Reading Time: 12 minutes | By: M.G Modibane | License: NCRDC3803
It is the first question every smart South African asks — usually right after an unregistered ‘agent’ promised them the moon: ‘Is debt review removal actually legal?’ The answer is yes, unambiguously — but only through specific routes written into the National Credit Act 34 of 2005 and related legislation. Everything outside those routes is either useless or a crime scene.
This guide maps every lawful exit from debt review, quotes the legal basis for each, prices them honestly, and shows you how to tell a legitimate removal from an illegal one before money changes hands.
If you want a registered debt counsellor to assess which route fits your file — free, in writing — WhatsApp +27 81 338 7728. Ours is NCRDC3803; verify it.
The Legal Landscape in One Table
| Instrument | Governs | What it does |
| National Credit Act 34 of 2005 | Debt review & clearance | Creates debt review — and the Form 19 exit (s71) |
| Magistrates’ Courts Act 32 of 1944 | Court orders | Provides rescission of orders granted in error |
| Insolvency Act 24 of 1936 | Sequestration | Structured route out of unpayable debt, ending in rehabilitation |
| National Credit Amendment Act | Recent reforms | Strengthened consumer protections in credit markets |
What the Law Actually Says About Exiting Debt Review
The National Credit Act did not design a trap. Section 71 obliges a debt counsellor to issue a clearance certificate once the restructured obligations are fulfilled, and obliges bureaus to update records within 20 business days. That is the primary exit — lawful, administrative, and available to everyone who qualifies.
Beyond completion, the courts provide two further routes. Rescission — setting aside the debt review order itself — applies where the order was granted in error or the consumer’s circumstances have fundamentally changed. Sequestration, under the Insolvency Act, is the court-supervised route for debt that genuinely cannot be serviced, concluding in rehabilitation. Three routes, three legal bases, zero ambiguity.
The Three Legal Exit Routes, Explained
Route one — Form 19 clearance. Available when all restructured unsecured debt is settled (or brought current under the Act’s criteria). Fastest and most common: typically 30–60 days from a complete file. Route two — rescission. A Magistrate’s Court application to set aside the order; appropriate for erroneous listings or materially improved finances. Typically 60–90 days where grounds are solid. Route three — sequestration. For unpayable debt: court application, trustee appointment, creditor claims, discharge and eventual rehabilitation. Longer and more profound, but a complete legal reset.
Which applies to you is a question of evidence, not opinion. That is why every legitimate removal begins with an audit, not a sales pitch.
What Is NOT Legal — and Why People Fall for It
Bureau ‘blocking’ — spamming disputes to temporarily hide accurate listings — is not removal. The data reverts, and in some configurations it exposes the consumer to fraud allegations. ‘Clearance certificates’ sold by anyone other than a registered debt counsellor are forgeries with no legal force. And no law permits the deletion of accurate, current debt without payment or court process — anyone promising that is describing a crime and inviting you to fund it.
The tell in every case is the same: the offer describes defeating the system rather than using it.
Who Should (and Shouldn’t) Proceed
✓ Signs You’re in the Right Place
- ✓ Names the exact legal route (Form 19, rescission, sequestration) that applies to your file
- ✓ Comes from a verifiable NCRDC registration
- ✓ Prices a fixed fee in writing, before work begins
- ✓ Quotes realistic timelines (weeks to months, never ‘7 days’)
- ✓ Welcomes regulator verification and written mandates
✗ Signs You Should Walk Away
- ✗ Promises removal of accurate, unpaid debt
- ✗ Sells ‘per listing’ deletion or bureau blocking
- ✗ Demands large upfront cash with no written mandate
- ✗ Cannot name the section of law relied upon
- ✗ Pressures you to decide immediately
Legal Routes at a Glance
| Route | Legal basis | Typical timeline | When it applies |
| Form 19 clearance | NCA s71 | 30–60 days | All restructured debt settled |
| Rescission | Magistrates’ Court | 60–90 days | Order granted in error / circumstances changed |
| Sequestration | Insolvency Act | 6–24 months | Debt genuinely unpayable |
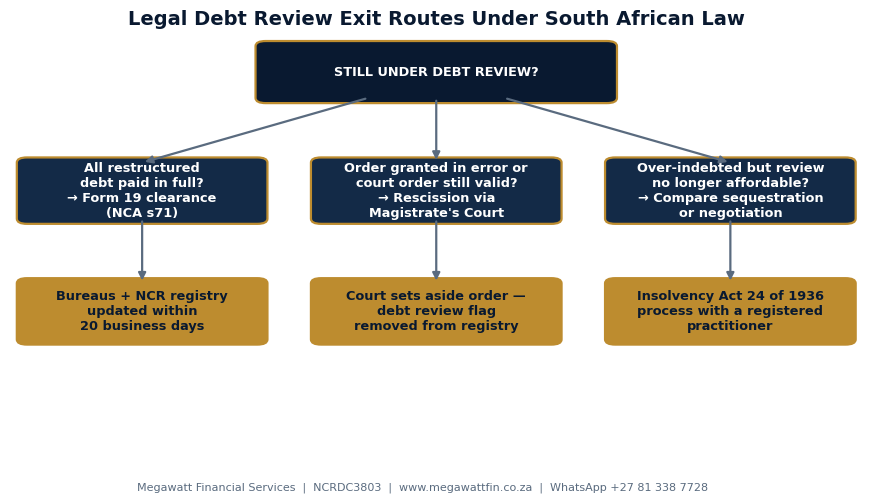
Infographic — Article 05 | Alt text: “is debt review removal legal infographic — Megawatt”
What This Means for You
- Regain full legal access to new credit
- End debt review distribution fees permanently
- Correct erroneous listings with documentary force
- Choose the route that fits your evidence — not a salesperson’s quota
- Hold every provider accountable through NCR and ombud channels
Common Mistakes to Avoid
I. Assuming all ‘removal’ offers are legal: The word covers both Form 19 clearance and bureau fraud. The legal basis — not the marketing — is the difference.
II. Choosing a route on emotion: Rescission when you need settlement-first wastes months. Let the audit decide, not hope.
III. Paying for expedited miracles: No fee accelerates statutory bureau windows. ‘Fast-track’ is a surcharge on impatience.
IV. Ignoring court orders in your file: Outstanding orders block administrative clearance until addressed — find out early.
V. Failing to verify the provider: An illegal process wastes money AND can damage your record further. Verify NCRDC3803 — or any number — first.
Legal Route Costs (2026 Ranges)
| Route | Typical market cost | Megawatt’s approach |
| Form 19 clearance | R3,500–R8,500 | Fixed quote after free assessment |
| Rescission application | R8,000–R20,000+ | Assessed individually, quoted in writing |
| Sequestration | R15,000–R40,000+ | Referred to specialist practitioners |
| ‘Guaranteed instant’ offers | R2,000–R10,000 | Scams — no lawful basis exists |
Frequently Asked Questions
Q: Can I exit debt review without paying all my debt?
Sometimes — via rescission where grounds exist, or sequestration where debt is unpayable. The route depends on evidence, not desire.
Q: Will removal erase my payment history?
No, and it shouldn’t. Lawful removal clears the review flag and corrects statuses; accurate history remains and is rebuildable.
Q: Is rescission the same as clearance?
No. Clearance (Form 19) certifies completion; rescission sets aside the order itself. Different law, different evidence, different outcomes.
Q: Can a magistrate refuse my rescission?
Yes — grounds must be proven. That is why reputable firms assess before applying, and why ‘guaranteed’ promises are red flags.
Q: Who can tell me which route I qualify for?
A registered debt counsellor, after an audit. Megawatt’s assessment is free and the answer comes in writing. WhatsApp +27 81 338 7728.
Why Choose Megawatt Financial Services?
| Feature | Megawatt | Other Providers |
| NCR Registration | NCRDC3803 | Varies |
| Free Assessment | Yes | Often R300–R500 |
| Fixed Pricing | No hidden fees | Often variable |
| All 4 Bureaus | Submitted to all | Often only 1–2 |
| Local Branches | Mokopane & Makhado | Often online-only |
| WhatsApp Support | +27 81 338 7728 | Often phone-only |
| Legal Representation | Included | Often extra cost |
Ready to Regain Control? Here’s Your Next Step
You’ve read the facts. Now take the two-minute step that changes everything. WhatsApp Megawatt Financial Services on +27 81 338 7728 — private, confidential, no paperwork required to start. Phone: 0861 MEGA-DC (0861 6342 32) | Email: info@megawattfin.co.za | Website: www.megawattfin.co.za
Our Branches
Branch 01 — Mokopane: 53 Retief Street, Office 1B Jaco Mari Building, Mokopane, 0600 | Branch 02 — Makhado: Office No: 5 Maranatha Centre, 93 Burger Street, Makhado, 0920 (Next to Old AVBOB)
| Trusted Debt Specialists Since 2019 | License: NCRDC3803 | Regain Control. Rebuild Your Future. |