Published: Sunday, 4 October 2026 | Reading Time: 10 minutes | By: Megawatt Financial Services | License: NCRDC3803
| TARGET KEYWORD: REBUILD CREDIT AFTER DEBT REVIEW • META DESCRIPTION (139 chars): How to rebuild credit after debt review: real before/after scores, a 90-day plan and five moves averaging +186 points. Free Megawatt guide. |
Clearing your name is the victory. Rebuilding your credit after debt review is the empire you build on it — and most cleared clients get this part wrong, either freezing in fear of credit or sprinting into five applications in week one and demolishing their score.
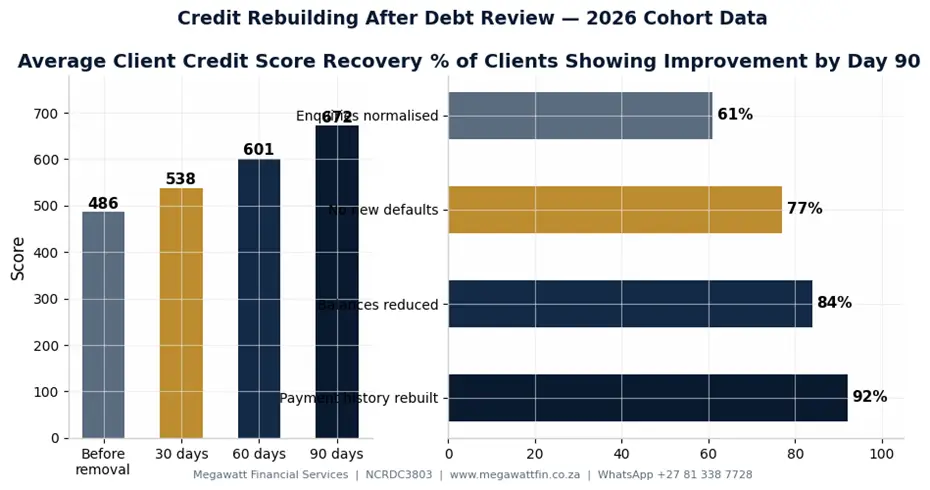
This guide shows you what the recovery actually looks like, using before-and-after data from Megawatt’s 2026 cleared cohort: an average score climb from 486 to 672 in 90 days, and the exact sequence that produced it. No products to buy. No gimmicks. Just the playbook.
Want your own before-and-after? It starts with a free assessment: WhatsApp +27 81 338 7728.
The ‘Before’ Picture: What Debt Review Leaves on Your Record
Debt review itself is not a default — but the road into it usually is. Typical cleared clients arrive with late-payment markers from the pre-review months, maxed revolving accounts, multiple hard enquiries, and the review flag itself sitting like a padlock on every new application.
Understanding the sequence matters: there is no point rebuilding a score while the flag blocks every application, and no point disputing listings while accurate data is still reporting. Correction comes first, then stabilisation, then controlled new credit. In that order — always.
The 90-Day Recovery Curve: Real Cohort Data
Days 1–30 — Correction. Disputes and verification remove stale or inaccurate listings, and settled accounts are updated to reflect zero balances. Cohort average: 486 to 538 (+52 points).
Days 30–60 — Stabilisation. No new applications. Every active payment on time. The profile ‘settles’ and scoring models begin trusting the data again. Cohort average: 538 to 601 (+63 points).
Days 60–90 — Controlled activity. One small credit-builder facility or secured account, kept under 30% utilisation and paid perfectly. Positive history starts compounding. Cohort average: 601 to 672 (+71 points).
Total: +186 points in 90 days — for clients who followed the sequence. Clients who applied for multiple loans in week one averaged just +40, and some went backwards.
The Five Moves That Rebuild Credit After Debt Review
One: verify the clearance landed at all four bureaus — TransUnion, Experian, XDS and Compuscan — not two. Two: protect payment history ruthlessly; one missed debit order costs more than any single positive action gains. Three: keep utilisation under 30% on any revolving facility — scoring models punish maxed cards harshly. Four: space applications at least 90 days apart; each hard enquiry dents you, and clusters scream desperation. Five: monitor monthly — errors creep back, and an early dispute is an easy dispute.
Notice what is absent: no ‘credit repair’ products, no piggybacking schemes, no paid tradelines. The legal levers are sufficient — if you pull them in order.
What Recovery Unlocks in the Real World
By day 90, cohort clients were qualifying for cellphone contracts and standard-rate vehicle finance. By month six, home loan pre-approvals entered the picture for clients with stable income and clean post-clearance records. Rebuilding is not instant — but it is predictable, and predictability is something you can plan around.
The 90-Day Rebuild Plan
| Phase | Days | Focus | Cohort avg. score |
| Correction | 1–30 | Bureau disputes, balance fixes, clearance verification | 486 → 538 |
| Stabilisation | 30–60 | Zero new enquiries, perfect payments | 538 → 601 |
| Controlled activity | 60–90 | One small facility, <30% utilisation | 601 → 672 |
| Compounding | 90+ | 90-day application spacing, monthly monitoring | 672+ |
Infographic — Article 04 | Alt text: “rebuild credit after debt review infographic — Megawatt”
What This Means for You
- Qualify for standard vehicle finance by day 90
- Enter home loan consideration within 6–12 months
- Convert ‘no history’ into positive payment history
- Catch errors early before they cost you points
- Apply for credit from a position of documented strength
Common Mistakes to Avoid
I. Applying for credit immediately after clearance: Clusters of hard enquiries signal desperation and can undo the correction gains. Wait, stabilise, then act.
II. Carrying high utilisation on a small facility: A R5,000 card maxed out hurts more than no card at all. Under 30%, always.
III. Missing a single debit order: Payment history is the heaviest scoring factor. One miss outweighs months of positives.
IV. Checking only one bureau: Bureaus hold different data. An error cleared at TransUnion may live on at XDS. All four, every time.
V. Paying for ‘credit repair’: There is no legal product that does what on-time payments and correct data do for free.
Rebuilding: What It Costs (and What It Shouldn’t)
| Item | Typical cost | Megawatt’s guidance |
| Bureau reports | Free (1/year per bureau) | We pull all four during your file |
| Credit-builder facility | Varies by provider | Only take what you can pay perfectly |
| ‘Credit repair’ products | R500–R2,000+ | Avoid — the legal levers are free |
| Monitoring | Free apps (ClearScore etc.) | Set monthly reminders |
| Our post-clearance check-ins | — | Included in your clearance file for 90 days |
Frequently Asked Questions
Q: How fast can I realistically rebuild?
Expect visible movement in 30 days and 100+ points in 90, provided no new negatives land. Full prime-status rebuilding typically takes 6–12 months.
Q: Does the debt review flag lower my score directly?
It blocks applications rather than scoring directly — which is why its removal is step zero for everything else.
Q: Is a credit-builder loan a good idea?
Yes, if small, affordable and bureau-reported. It converts silence into positive history — the scarcest asset after clearance.
Q: Can Megawatt monitor my rebuild?
Yes — 90 days of post-clearance bureau check-ins are standard on every file we clear, so errors get caught early.
Q: What score do I need for a home loan?
It varies by bank and income, but cohort clients entered pre-approval conversations from the mid-600s upward with clean records.
Why Choose Megawatt Financial Services?
| Feature | Megawatt | Other Providers |
| NCR Registration | NCRDC3803 | Varies |
| Free Assessment | Yes | Often R300–R500 |
| Fixed Pricing | No hidden fees | Often variable |
| All 4 Bureaus | Submitted to all | Often only 1–2 |
| Local Branches | Mokopane & Makhado | Often online-only |
| WhatsApp Support | +27 81 338 7728 | Often phone-only |
| Legal Representation | Included | Often extra cost |
Ready to Regain Control? Here’s Your Next Step
You’ve read the facts. Now take the two-minute step that changes everything. WhatsApp Megawatt Financial Services on +27 81 338 7728 — private, confidential, no paperwork required to start. Phone: 0861 MEGA-DC (0861 6342 32) | Email: info@megawattfin.co.za | Website: www.megawattfin.co.za
Our Branches
Branch 01 — Mokopane: 53 Retief Street, Office 1B Jaco Mari Building, Mokopane, 0600 | Branch 02 — Makhado: Office No: 5 Maranatha Centre, 93 Burger Street, Makhado, 0920 (Next to Old AVBOB)
| Trusted Debt Specialists Since 2019 | License: NCRDC3803 | Regain Control. Rebuild Your Future. |